RBI DG Murmu: AI must widen banking access, improve customer experience – not just cut costs
Speaking at the CNBC-TV18 Banking Transformation Summit, RBI Deputy Governor Shirish Chandra Murmu said the next phase of Indian banking would be shaped by “responsible innovation, governance, prudence, and trust”, with AI playing a role in making financial services more accessible.
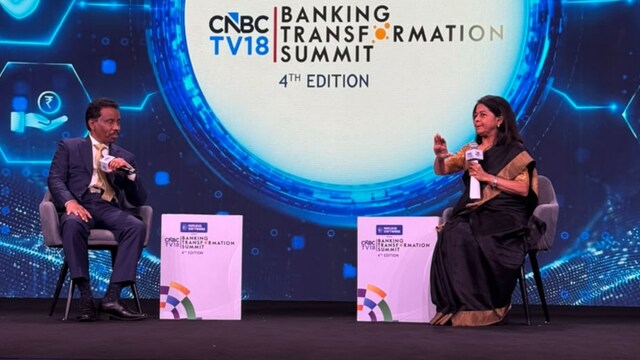
Speaking at the CNBC-TV18 Banking Transformation Summit, Murmu said the next phase of Indian banking would be shaped by “responsible innovation, governance, prudence, and trust”, with AI playing a role in making financial services more accessible.
“What formal finance lacked was not the information, but a means of using it. And even today, in far more sophisticated markets, economic capacity often exists quietly, waiting for formal systems to develop the means to recognise it. And today, the means have arrived in the form of artificial intelligence. The question before us is how well and how responsibly we choose to use it,” Murmu said.
Also read: RBI MPC minutes turn slightly hawkish, leave door open for rate hike this year
He said rapid innovation needs to be accompanied by safeguards, judgement and accountability.
“I read that as a statement of intent and exhort you to ensure that innovation is rapid, at the same time accompanied by robust safeguards, applied with judgement and underpinned by accountability,” Murmu said.
AI can widen financial inclusion
Murmu said AI could play a role in the next phase of financial inclusion by helping banks recognise economic capability across differences in language, location, livelihood, gender and channels.
“AI has a meaningful role to play here, helping the system recognise capability wherever it is expressed differently across language, location, livelihood, gender, and channel, and using the data prudently to make financial services more accessible,” he said.
He said the Financial Inclusion Index rose to 70 in March 2026 from 67 a year earlier, with the improvement driven largely by usage rather than access.
Murmu also highlighted differences in customer needs, saying younger and digitally confident customers may prioritise speed and convenience, while older customers or those less comfortable with technology may prefer assisted access, personal interaction and reassurance on security.
As banking becomes more complex, he said, there needs to be clarity on responsibility for product suitability, data use, service quality and continuity across the delivery chain.
Human judgement remains critical
Murmu said banks need people who can understand new systems, challenge models, oversee external providers and connect technological changes with financial and conduct outcomes.
“As machines take over more of the routine tasks, what becomes indispensable is human judgement. Validating a model, assessing its outcome, and stopping it when it begins to go rogue, and this shift requires institutions to reskill and to grow their capability,” he said.
Also read: Fedbank Financial Services board to consider ₹2,500 crore fundraise through debt
He said intelligence in banking should not be viewed only through the lens of artificial intelligence. According to Murmu, it has four levels: analytical intelligence involving data, models and technology; human intelligence involving experience, knowledge and judgement; governance intelligence involving boards and senior management; and collective intelligence emerging when information is pooled across banks.
“The value lies less in any one of these than in how well they are combined,” he said.
AI can help address credit gaps
Murmu also pointed to a shift in the share of new businesses entering the formal credit system. He said 52% of fresh businesses entered the formal credit system in 2022-23, but the figure fell to 42% by 2025-26, even as outstanding commercial credit grew 14% during the year.
He said lenders now have access to richer data and stronger analytical capabilities, and argued that technology could help banks better understand customers who have historically remained outside the formal credit system.
“These alternative data offer a genuine opportunity to bring credit-invisible customers into the formal system, and AI can help close that gap,” Murmu said.
He cited data points such as cash flows, GST filings, utility payments, e-commerce records, mobile usage, agricultural data and geospatial data as sources that can complement traditional lending information.
Murmu also said AI could help banks process information that is not readily available in conventional formats, including audio descriptions from borrowers, images of crops or inventory and weather patterns affecting seasonal cash flows, provided such information is captured with consent and tested for reliability and bias.
AI productivity must translate into better banking
Murmu said AI can reduce the time spent on routine tasks such as reconciling records, summarising credit files and answering routine queries, but banks should assess productivity beyond cost savings.
“Productivity in banking is not merely output per employee or the cost-to-income ratio. It is whether the same institution, with the same resources, reaches a borrower it could not reach before, resolves a grievance that would earlier have remained pending, or prices risk more accurately,” he said.
“If AI compresses costs without widening reach or improving customer experience, we shall have automated the existing system rather than improved it,” Murmu said.
He also said AI could help banks identify emerging weaknesses in areas such as fraud, conduct, operations and cyber risk by analysing structured indicators alongside audit observations, incident narratives, customer complaints and system logs.
At the same time, banks must retain the judgement, capability and alternative arrangements needed to intervene when AI systems fail or behave unexpectedly, Murmu said.
Original source: https://www.cnbctv18.com/technology/